Two distinct robotics sectors received detailed analysis in a technical report released this week, pairing insights from a surgical robotics implementation with guidance on warehouse automation deployment. The publication arrives as both industries face mounting pressure to demonstrate return on investment while navigating workforce constraints and regulatory frameworks that vary significantly between medical and industrial applications.
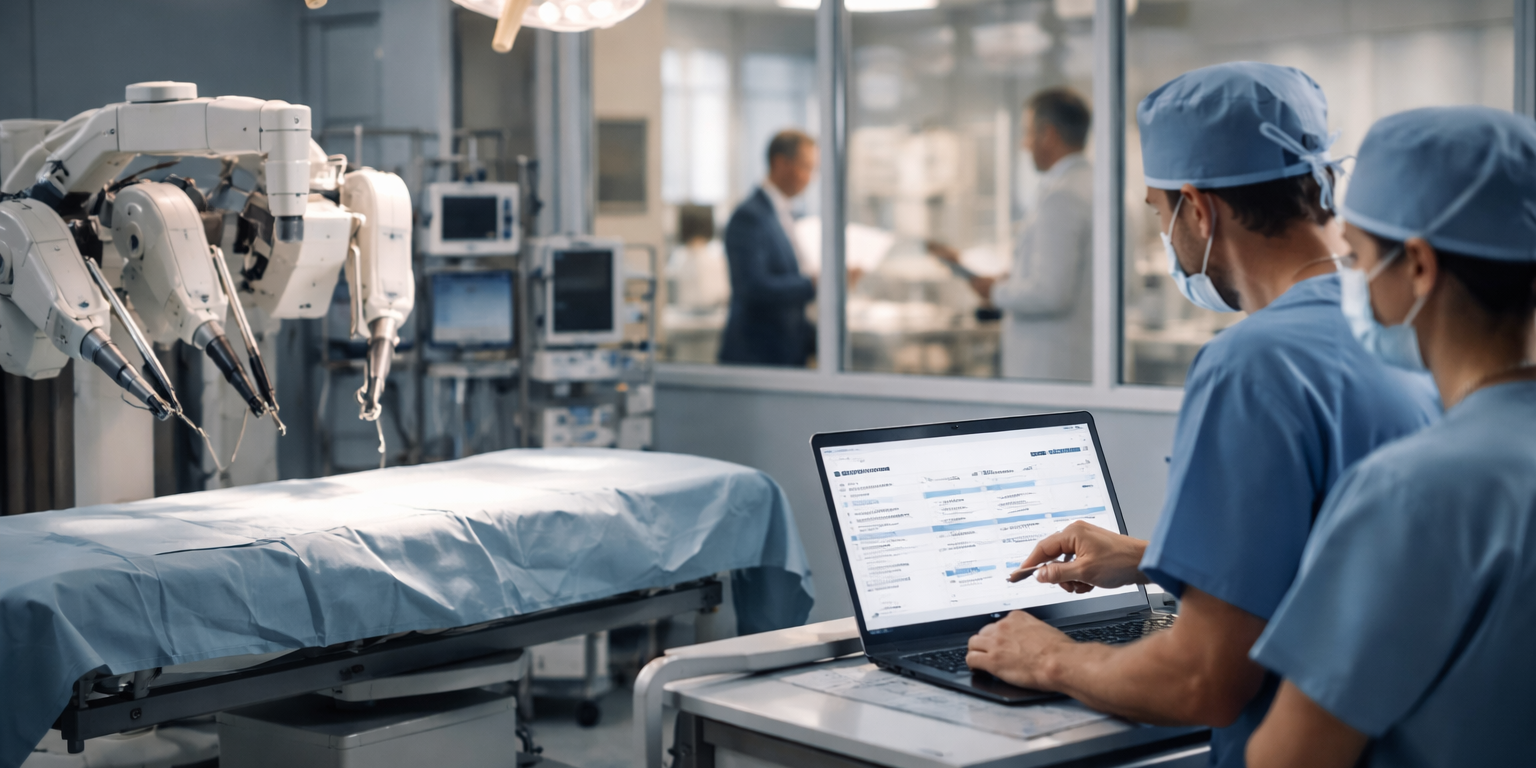
Surgical robotics continues to evolve beyond the dominant da Vinci platform model, with newer entrants targeting specific procedures rather than general-purpose surgical assistance. The case study portion of the report examines how hospitals evaluate robotic systems based on procedure volume, surgeon training requirements, and device footprint within existing operating room infrastructure. Integration timelines for surgical robots typically span twelve to eighteen months from purchase decision to full operational deployment, a period driven less by technical complexity than by clinical validation protocols and staff certification requirements. Hospitals purchasing surgical robots in 2026 face additional considerations around interoperability with electronic health record systems and data capture requirements mandated by value-based care contracts.
The warehouse automation segment addresses a different set of constraints. Mobile robot deployments in fulfillment centers now routinely involve fleets exceeding one hundred units, but the report emphasizes that fleet size alone does not determine project success. Deployment velocity matters more than final robot count for most operations, with the analysis pointing to facilities that achieve full operational status within four to six months as the benchmark. Those timelines depend on pre-deployment site mapping accuracy, warehouse management system integration depth, and whether the facility operates single-shift or continuous schedules. The report draws particular attention to the challenge of operating autonomous mobile robots in mixed environments where human workers, forklifts, and automated guided vehicles share the same physical space without centralized coordination systems.
Both domains share common technical ground in sensor fusion, path planning, and obstacle avoidance, yet the regulatory and operational contexts create divergent priorities. Surgical robots operate in controlled environments with known variables but face stringent safety certification and liability frameworks. Warehouse robots navigate dynamic, unpredictable spaces but benefit from industrial safety standards that permit rapid iteration and deployment. The report notes that venture funding for surgical robotics companies totaled approximately $2.3 billion across 2025, while warehouse automation attracted $4.1 billion during the same period, reflecting investor confidence in near-term revenue potential for logistics applications versus the longer development and approval cycles in medical robotics. Companies operating in both sectors, such as those developing autonomous navigation stacks applicable to hospital delivery robots and warehouse transporters, find themselves balancing these different timelines and risk profiles.
What to Watch: Track FDA clearance announcements for new surgical robotic platforms through Q4 2026, particularly those targeting orthopedic and cardiovascular procedures outside traditional laparoscopic surgery. Monitor quarterly earnings calls from major warehouse automation providers including Locus Robotics, AutoStore, and Symbotic for deployment numbers and customer retention metrics. Observe whether surgical robotics companies begin offering usage-based pricing models similar to robotics-as-a-service contracts now common in logistics, a shift that would signal changing hospital procurement strategies heading into 2027.