Healthcare Triangle projects Roboticom's industrial robotics division will generate $153.5 million in revenue within five years of acquisition, according to management forecasts disclosed alongside the letter of intent signed this week. The Pleasanton, California-based cloud services and IT company has never operated in the robotics sector. Roboticom's current client base spans automotive assembly operations and electronics manufacturing facilities requiring sub-millimeter positioning accuracy.
Healthcare Triangle built its $50 million annual revenue business around cloud infrastructure and data analytics for hospitals and life sciences companies. The Roboticom acquisition represents a categorical shift in operational focus. Suresh Venkatachari, HCTI's chief executive, spent the past eighteen months evaluating entry points into industrial automation after the company's healthcare IT growth plateaued at 12 percent year-over-year in fiscal 2025. Letters of intent typically precede 60 to 90 days of due diligence before definitive purchase agreements, though deal terms including valuation and payment structure remain undisclosed. Roboticom operates three engineering centers and maintains partnerships with component suppliers in precision motion control and machine vision systems.
The five-year financial projections included in the announcement outline a path to $64 million in adjusted operating contribution, implying 42 percent margins if revenue targets materialize. Those figures assume Roboticom wins contracts in battery manufacturing automation, a segment where precision welding and assembly tolerances have tightened as cell chemistries evolved. Current Roboticom installations include delta robots for high-speed pick-and-place operations running at 120 cycles per minute and SCARA configurations for electronics testing. The company developed proprietary control software that integrates with factory execution systems from Siemens and Rockwell Automation. HCTI management believes cross-selling opportunities exist between Roboticom's manufacturing clients and Healthcare Triangle's data analytics platform, though the technical overlap remains unclear. Industrial customers typically purchase robotics through systems integrators rather than directly from automation providers, adding distribution complexity Healthcare Triangle has not previously navigated.
Roboticom's existing order backlog and contracted revenue were not disclosed in the announcement. The company competes with established providers including FANUC, ABB, and Yaskawa in segments where brand recognition and installed base drive purchasing decisions. Smaller precision robotics firms have struggled to scale beyond niche applications without access to capital for geographic expansion and product line extensions. Healthcare Triangle's balance sheet showed $8.2 million in cash and equivalents as of its most recent quarterly filing, suggesting debt financing or equity raises may be required to close the transaction. The company's stock trades on the NASDAQ under ticker HCTI at a market capitalization near $35 million. Acquiring a business projected to reach $153.5 million in revenue would represent a transformative bet for a firm of that size, particularly when entering an unfamiliar market with entrenched competitors and long sales cycles.
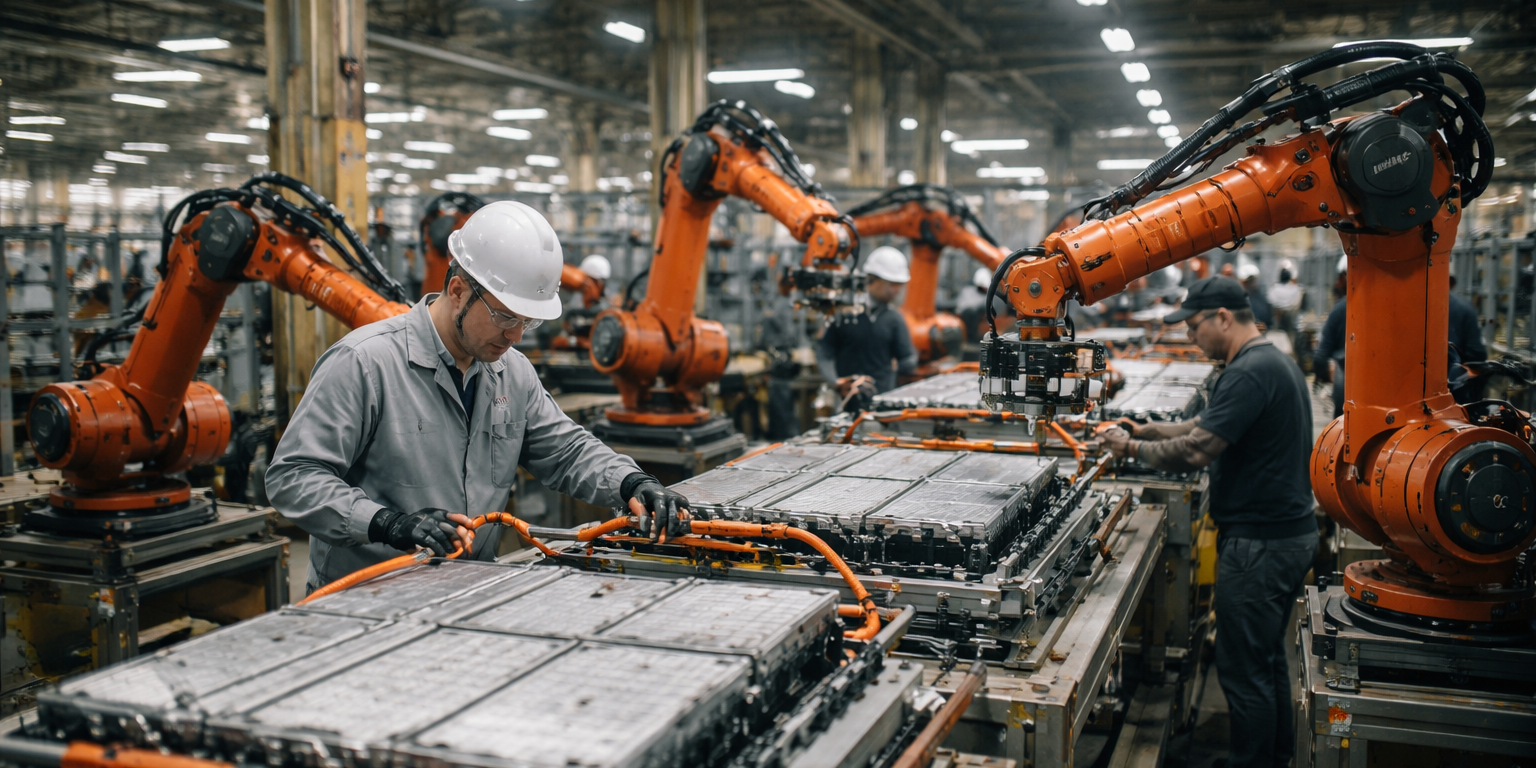
Manufacturing automation spending has concentrated in electric vehicle battery production and semiconductor packaging, two areas where precision tolerances directly impact product yield and warranty costs. Roboticom's engineering team includes specialists in vibration dampening and thermal compensation for robotic arms operating in temperature-variable environments. Those capabilities matter in battery cell assembly, where dimensional tolerances of 50 microns determine seal integrity. The question facing Healthcare Triangle is whether Roboticom's technology differentiation justifies the operational challenges of managing a capital equipment business alongside a software services operation. Due diligence will likely focus on customer concentration, recurring revenue from service contracts, and the age of Roboticom's installed base. Systems sold five to seven years ago are approaching refresh cycles, creating potential for replacement sales if customer relationships remain strong.
What to Watch: Healthcare Triangle must file definitive acquisition terms within 90 days if due diligence proceeds as planned. Watch for updates on financing arrangements, particularly whether HCTI pursues debt or dilutive equity to fund the purchase. Roboticom's 2027 revenue performance will test whether the $153.5 million five-year projection reflects conservative planning or aggressive assumptions. Monitor whether HCTI retains Roboticom's existing management team, a common indicator of confidence in operational continuity during industrial acquisitions.