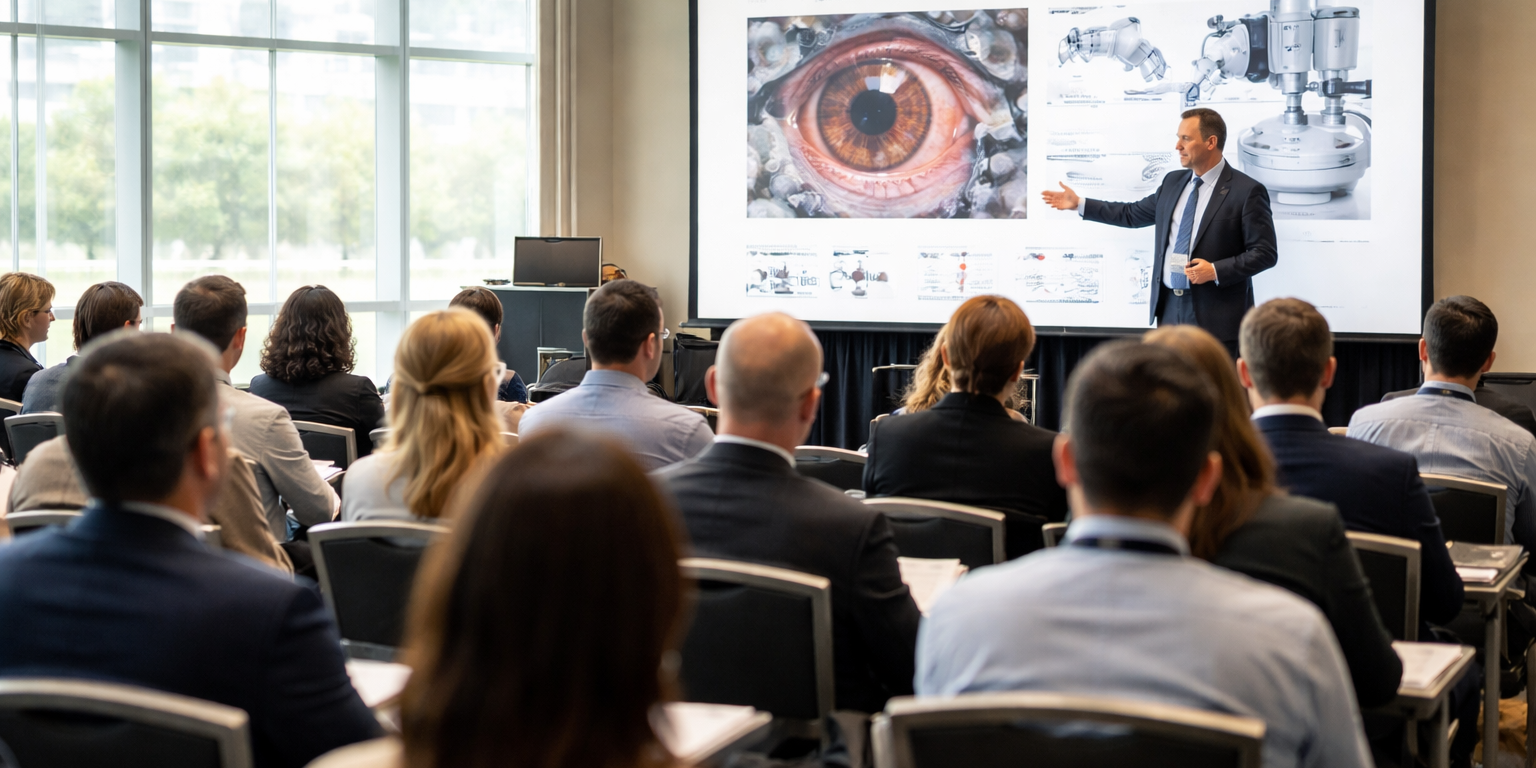
Medevise Consulting announced September 24 that it will host a workshop examining the regulatory and commercial barriers facing robotic systems in ophthalmic surgery during the American Academy of Ophthalmology annual meeting in New Orleans. The session, titled Robotics in Ophthalmology: What It Takes to Leapfrog Today's Standard of Care, targets a question that has frustrated device manufacturers for years: why manual phacoemulsification and vitrectomy techniques still dominate despite billions invested in autonomous alternatives. Medevise has not disclosed the workshop date or venue within the AAO conference schedule, which runs October 16-19, 2026 at the Ernest N. Morial Convention Center. The firm specializes in regulatory strategy for ophthalmic and surgical device companies navigating FDA 510(k) and de novo pathways.
The timing reflects intensifying competition in robotic eye surgery, where at least four companies now have systems in clinical use or advanced trials. Johnson & Johnson Vision's Catalys femtosecond laser platform has held the market lead since its 2011 clearance, but the system remains limited to anterior capsulotomy and lens fragmentation during cataract procedures. Surgeons still complete the bulk of the procedure manually. Preceyes, a Dutch startup acquired by Gerresheimer in 2022, received FDA clearance in 2024 for its teleoperated robot targeting retinal vein cannulation and subretinal injection, procedures requiring sub-millimeter precision beyond human hand stability. Alcon and Zeiss both have investigational systems in U.S. trials, though neither has published enrollment data. The Alcon platform, developed in partnership with ETH Zurich, automates portions of vitrectomy. Zeiss has disclosed little about its approach beyond patent filings describing force-feedback mechanisms for membrane peeling. Industry watchers expect both companies to showcase updated prototypes at AAO 2026, making Medevise's workshop well-positioned to capture executive attention.
Reimbursement remains the central obstacle. Medicare's Hospital Outpatient Prospective Payment System does not provide incremental payment for robotic-assisted cataract surgery, treating it identically to manual phaco under Ambulatory Payment Classification 5492. That classification pays approximately $920 in 2026, covering facility costs but not physician fees. Without a premium, hospitals see robotic systems as capital expenses that extend procedure time without financial benefit. The math changes only in specific cases where precision justifies premium billing, such as complex pediatric cataracts or secondary intraocular lens placement. Vitreoretinal surgery offers slightly better economics because membrane peeling and vein cannulation carry higher technical difficulty ratings, but volumes remain low compared to cataracts, where the U.S. market exceeds 4 million procedures annually. Medevise has advised companies including Alcon and Bausch + Lomb on reimbursement strategy, making the firm's workshop a potential preview of how manufacturers plan to argue for separate payment codes.
The regulatory path also constrains innovation. FDA has classified most ophthalmic robots as Class II devices requiring 510(k) clearance, a pathway designed for incremental improvements to existing device types. But the predicate device problem arises immediately: what constitutes a valid predicate when no widely-used robotic eye surgery system exists? Preceyes solved this by pursuing de novo classification, arguing its teleoperated robot represented a new device type. That route took six years from investigational device exemption to clearance. Companies seeking faster market entry face a choice between arguing their system equals an existing predicate, which limits claims about superiority, or accepting the longer de novo timeline. Medevise's client list suggests the firm will address this tradeoff directly, likely presenting case studies from recent clearances. The workshop format, which Medevise describes as convening regulatory, reimbursement, and surgical robotics leaders, suggests a panel structure rather than didactic presentations, potentially including FDA officials speaking in personal capacity.
What to Watch: AAO 2026 exhibitor lists, expected in late September, will reveal which companies have secured booth space large enough for live surgical demonstrations. Alcon and Zeiss typically reserve prominent positions, but startup participation will signal how crowded the ophthalmic robotics field has become. Medevise may announce workshop panelists by early October, offering clues about which regulatory and clinical voices will shape the discussion. Post-workshop, watch for companies issuing updated investor presentations citing panel conclusions, a common pattern when consulting firms facilitate industry consensus on commercial strategy.